

8 Mistakes New Small Business Owners Make and How to Avoid Them
Starting a business comes with plenty of opportunities to make costly mistakes. Learn eight common mistakes new small business owners make, from failing to plan ahead and overspending to underpricing and trying to do everything themselves, plus how StartSmart can help you build a stronger financial plan for one business completely free.

Why New Business Owners Need to Create Financial Projections for Their Business Plans
Financial projections help new business owners understand startup costs, estimate revenue and expenses, anticipate cash flow needs, evaluate profitability, and build a stronger business plan. Learn why projections matter and how StartSmart can help you automatically create a complete financial plan and supporting financial projections for one business completely free.
6 Tips to Create Successful Financial Projections for a New Business
Creating realistic financial projections can help new business owners better understand expenses, sales, cash flow, assets, liabilities, operations, and break-even requirements. Learn six important tips for building stronger projections and how StartSmart can help you automatically create a complete financial plan and supporting projections for one business completely free.
More articles to help you make smarter financial decisions
Client Advisory Services and fractional CFO services both help businesses move beyond historical accounting into financial planning and decision support, but they aren't necessarily the same thing. CAS can span outsourced accounting, controllership, forecasting, reporting, and advisory, while fractional CFO services typically represent a higher level of ongoing financial leadership. This guide explains the differences, overlap, typical responsibilities, and how accounting firms can determine where their CAS offering should sit on the advisory spectrum.
Client Advisory Services vs. Fractional CFO: What's the Difference?
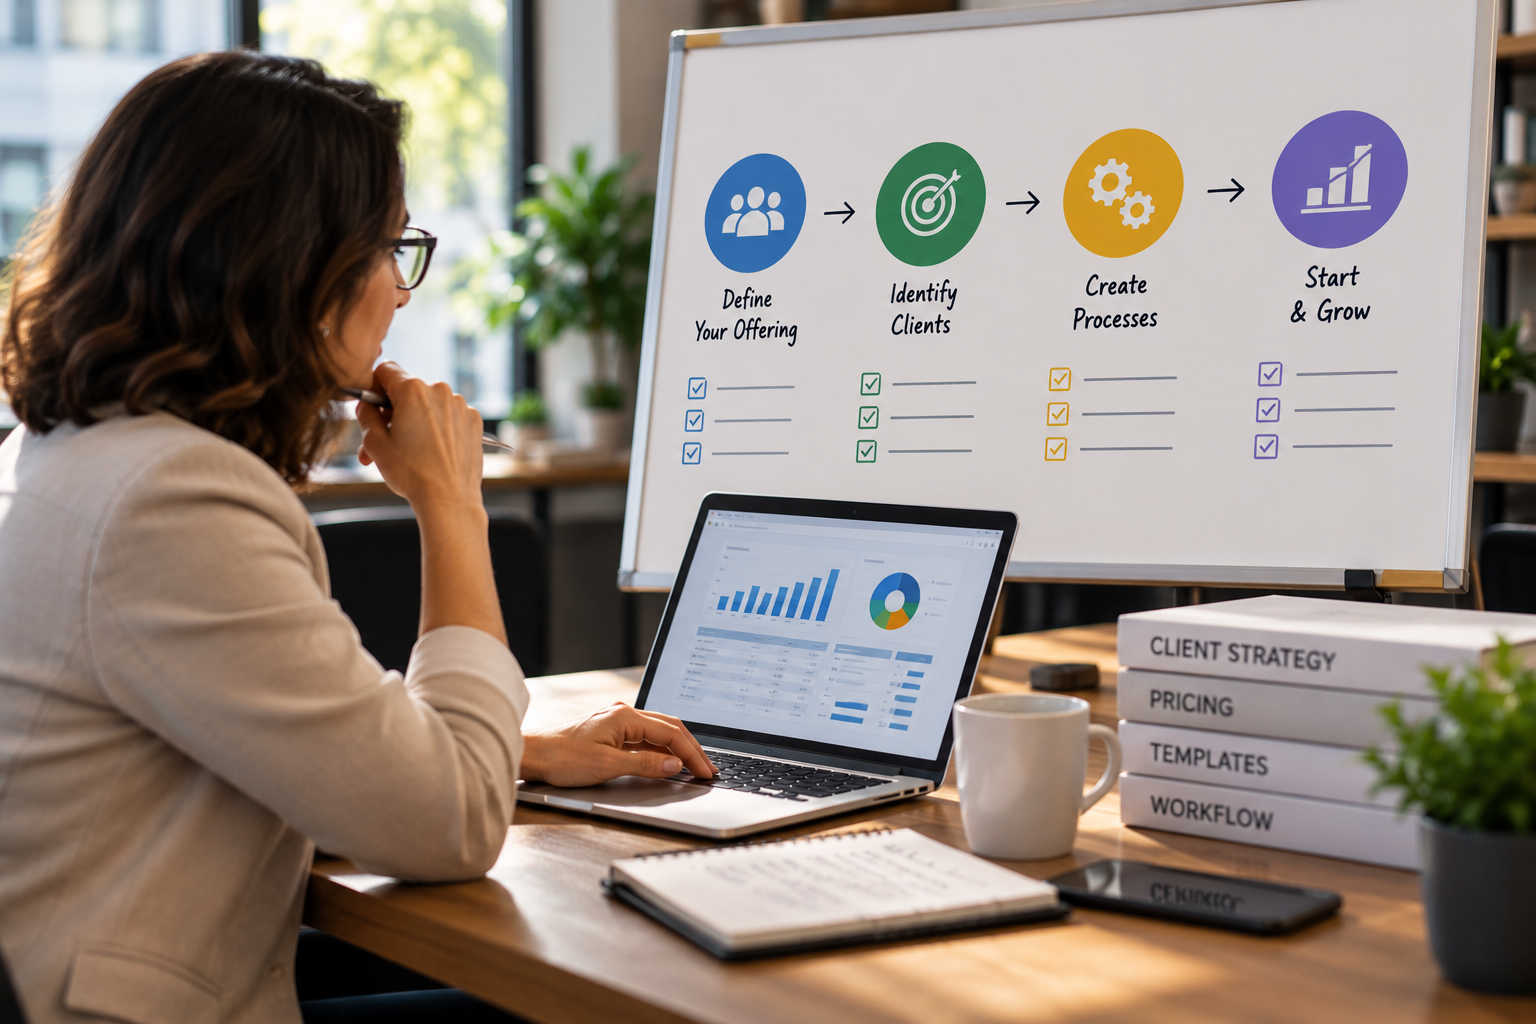
Starting Client Advisory Services requires more than adding forecasting or advisory meetings to an existing accounting practice. Firms need to define their services, identify right-fit clients, standardize delivery, establish recurring workflows, select technology, price engagements appropriately, and create a consistent client experience. This guide provides a practical framework for accounting and bookkeeping firms building a CAS offering.
How to Start Client Advisory Services at Your Accounting Firm
Client Advisory Services (CAS) expand the role of accounting and bookkeeping firms beyond transactional and compliance work into ongoing financial operations, analysis, forecasting, planning, and business advisory. This guide explains what CAS means, common CAS services, how CAS differs from traditional accounting and fractional CFO services, which clients may benefit, and how technology can help firms deliver advisory services efficiently and at scale.
What Are Client Advisory Services (CAS)? A Guide for Accounting Firms
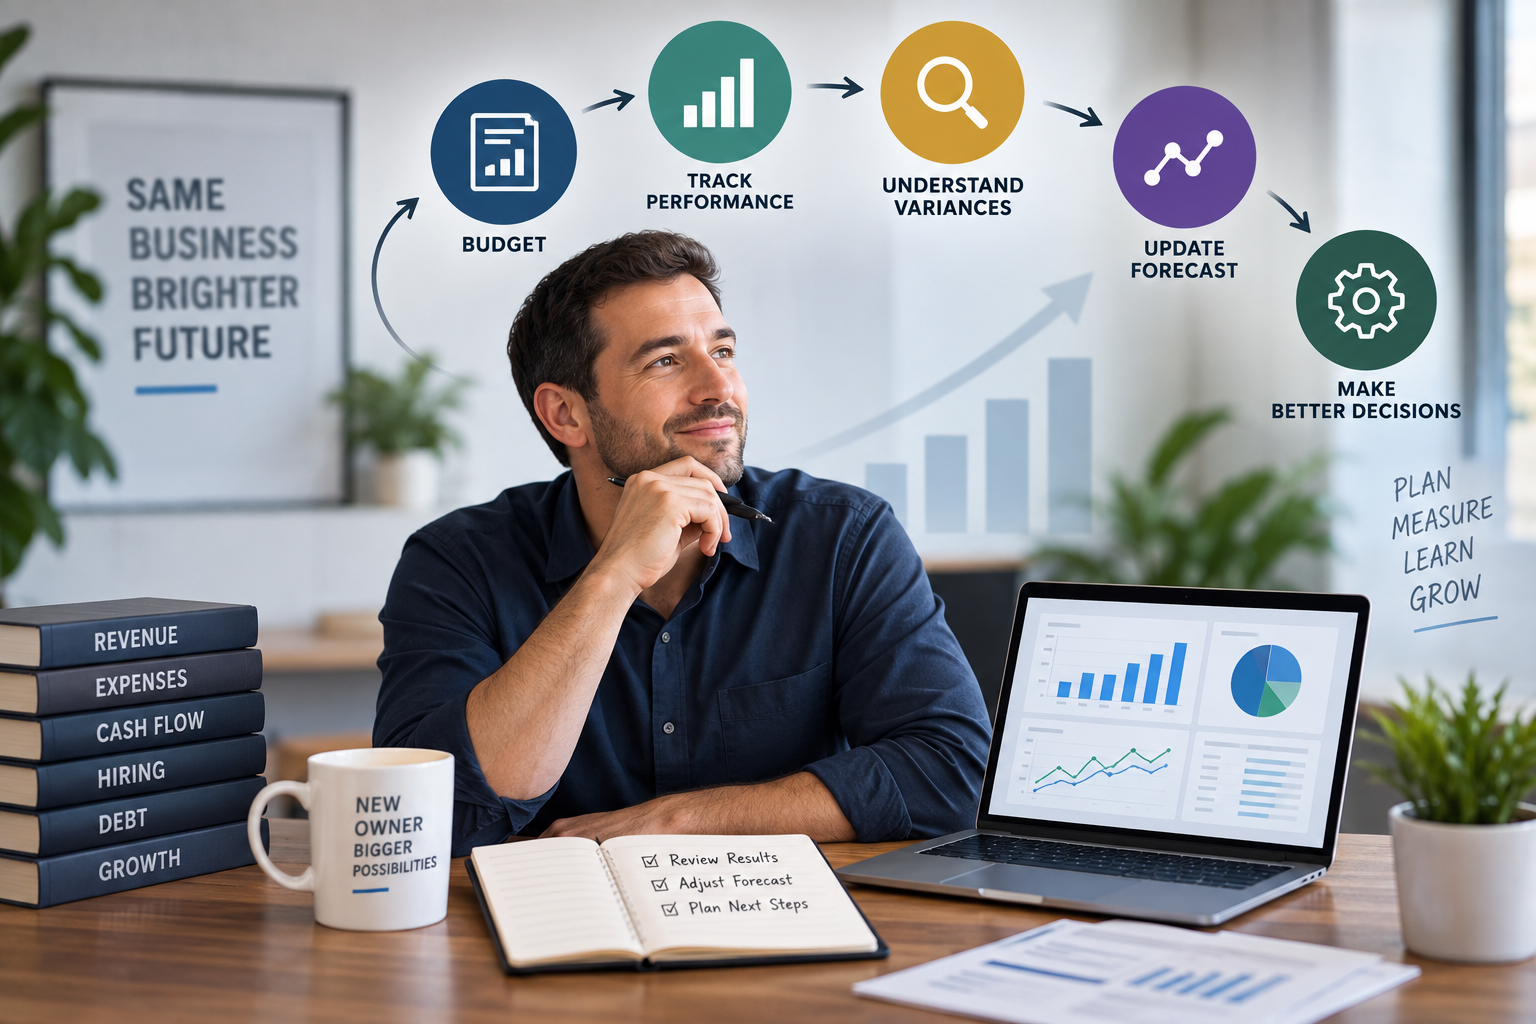
Closing an acquisition changes the financial question from “Should I buy this business?” to “How is the business actually performing under my ownership?” This guide explains how acquisition entrepreneurs can turn their pre-acquisition assumptions into an operating financial plan, establish a budget, monitor cash flow and financial health, compare actual results with expectations, update forecasts, and make informed decisions during the first year as owner.
How to Build a Financial Plan After Buying a Business
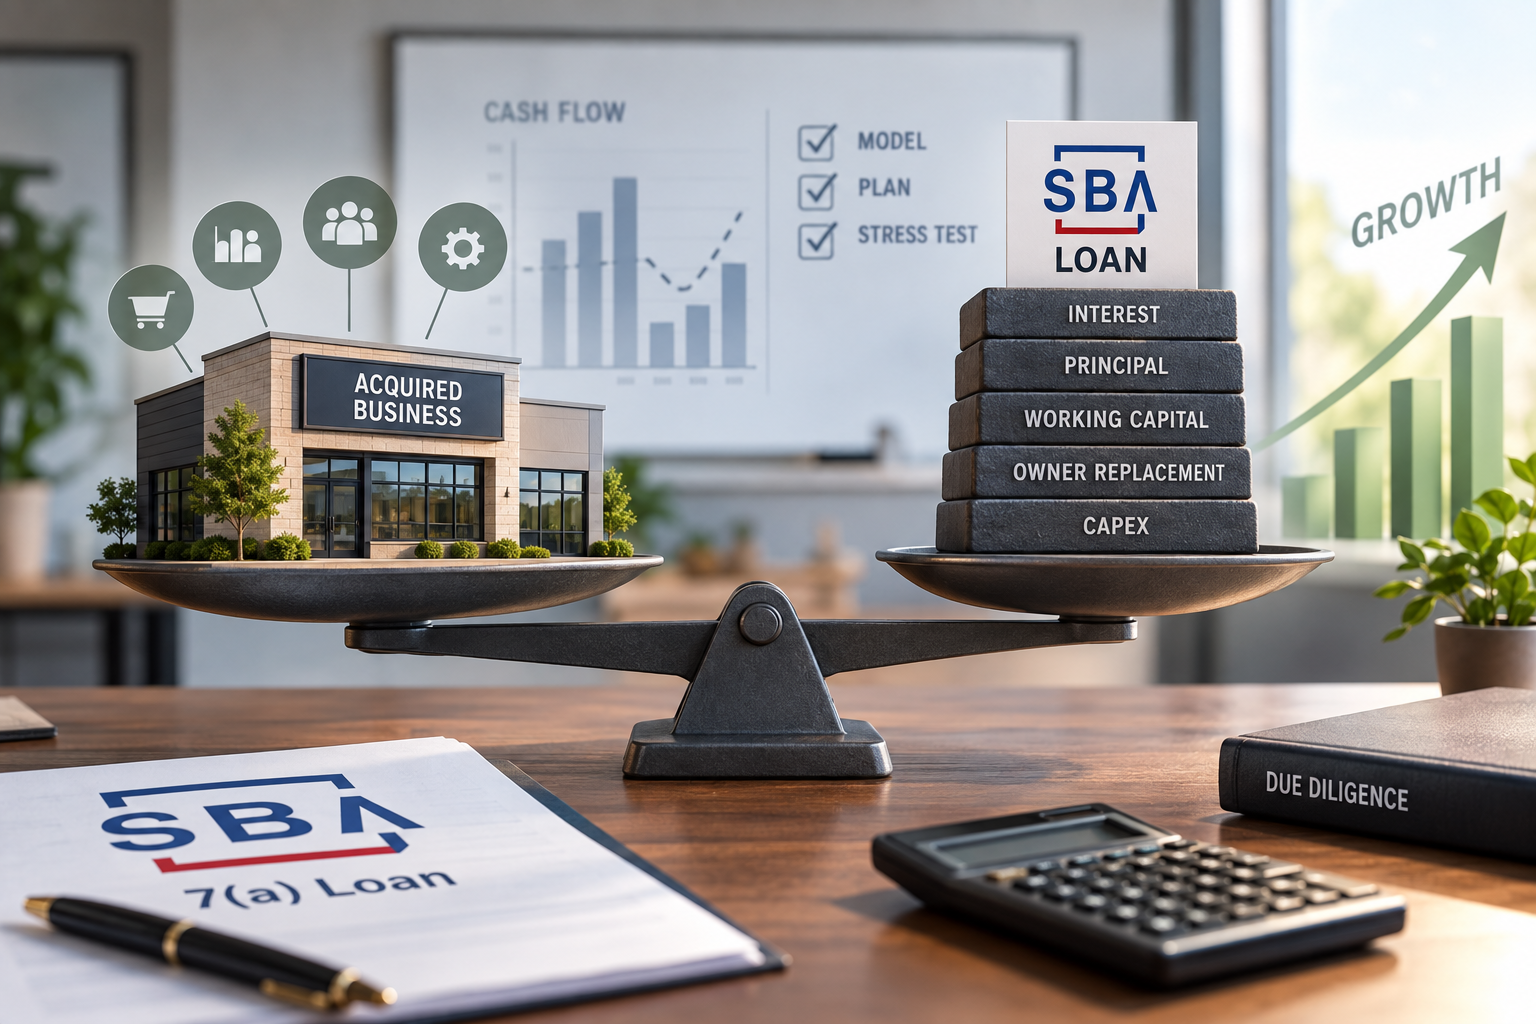
SBA 7(a) financing can be used for qualifying business acquisitions, but obtaining financing is only part of the analysis. This guide explains how prospective buyers can model acquisition debt alongside revenue, expenses, cash flow, working capital, hiring, and downside scenarios to understand how the business could perform after closing.
Buying a Business With an SBA Loan: How to Model the Acquisition
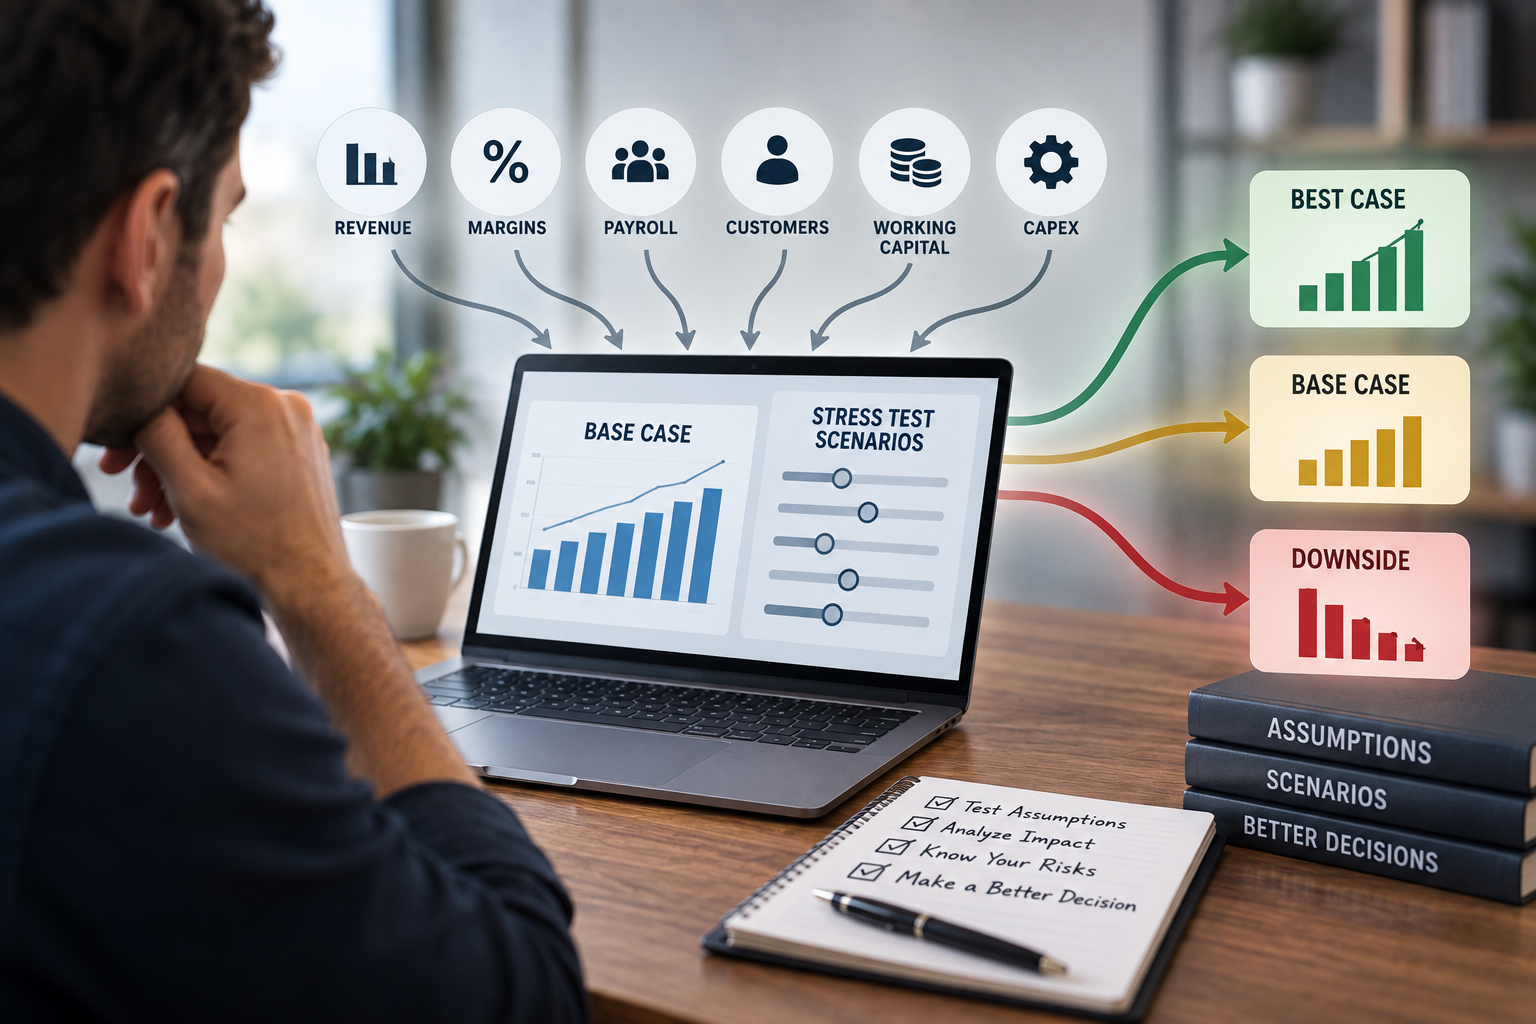
Stress testing a business acquisition means modeling what could happen if important assumptions don't go according to plan. This guide explains how prospective buyers can test revenue declines, margin pressure, customer losses, higher payroll, acquisition debt, working-capital changes, and other downside scenarios before buying a business.
How to Stress Test a Business Before You Buy It
Historical financial statements show how a business performed under its current owner, but acquisition financial projections help estimate what could happen after ownership changes. This guide explains how to build projections for an existing business using historical performance, future assumptions, acquisition financing, staffing changes, operating expenses, working capital, and cash flow.
How to Build Financial Projections When Buying a Business
A profitable business isn't necessarily a financially healthy business. This guide explains how prospective buyers can evaluate the financial health of a business for sale by examining profitability, liquidity, solvency, operating efficiency, capitalization, financial trends, and the relationships between key financial metrics.
How to Evaluate the Financial Health of a Business for Sale
Entrepreneurship through acquisition allows entrepreneurs to become business owners by purchasing an established company instead of starting one from scratch. This guide explains how ETA works, the different acquisition models, how buyers find and evaluate businesses, financing options, financial due diligence, forecasting, and what happens after the acquisition.
What Is Entrepreneurship Through Acquisition? A Guide to Buying a Business Instead of Starting One
