Starting a business is exciting, but turning an idea into a successful company requires more than a good product or service.
New business owners have to make decisions about pricing, spending, customers, technology, hiring, cash flow, and dozens of other areas, often without the experience or resources of a larger company.
Some mistakes are inevitable. Others can be avoided with better planning and a clearer understanding of your business before you commit significant time and money.
Here are eight common mistakes new small business owners make and what you can do to avoid them.
1. Starting Without a Clear Financial Plan
A great business idea doesn't automatically make a financially viable business.
Before launching, you should have a realistic understanding of how much money you'll need to get started, what it will cost to operate the business, how much revenue you expect to generate, and how long it may take to become profitable.
Your financial plan should consider factors such as startup costs, pricing, sales expectations, operating expenses, staffing, financing, cash flow, and break-even requirements.
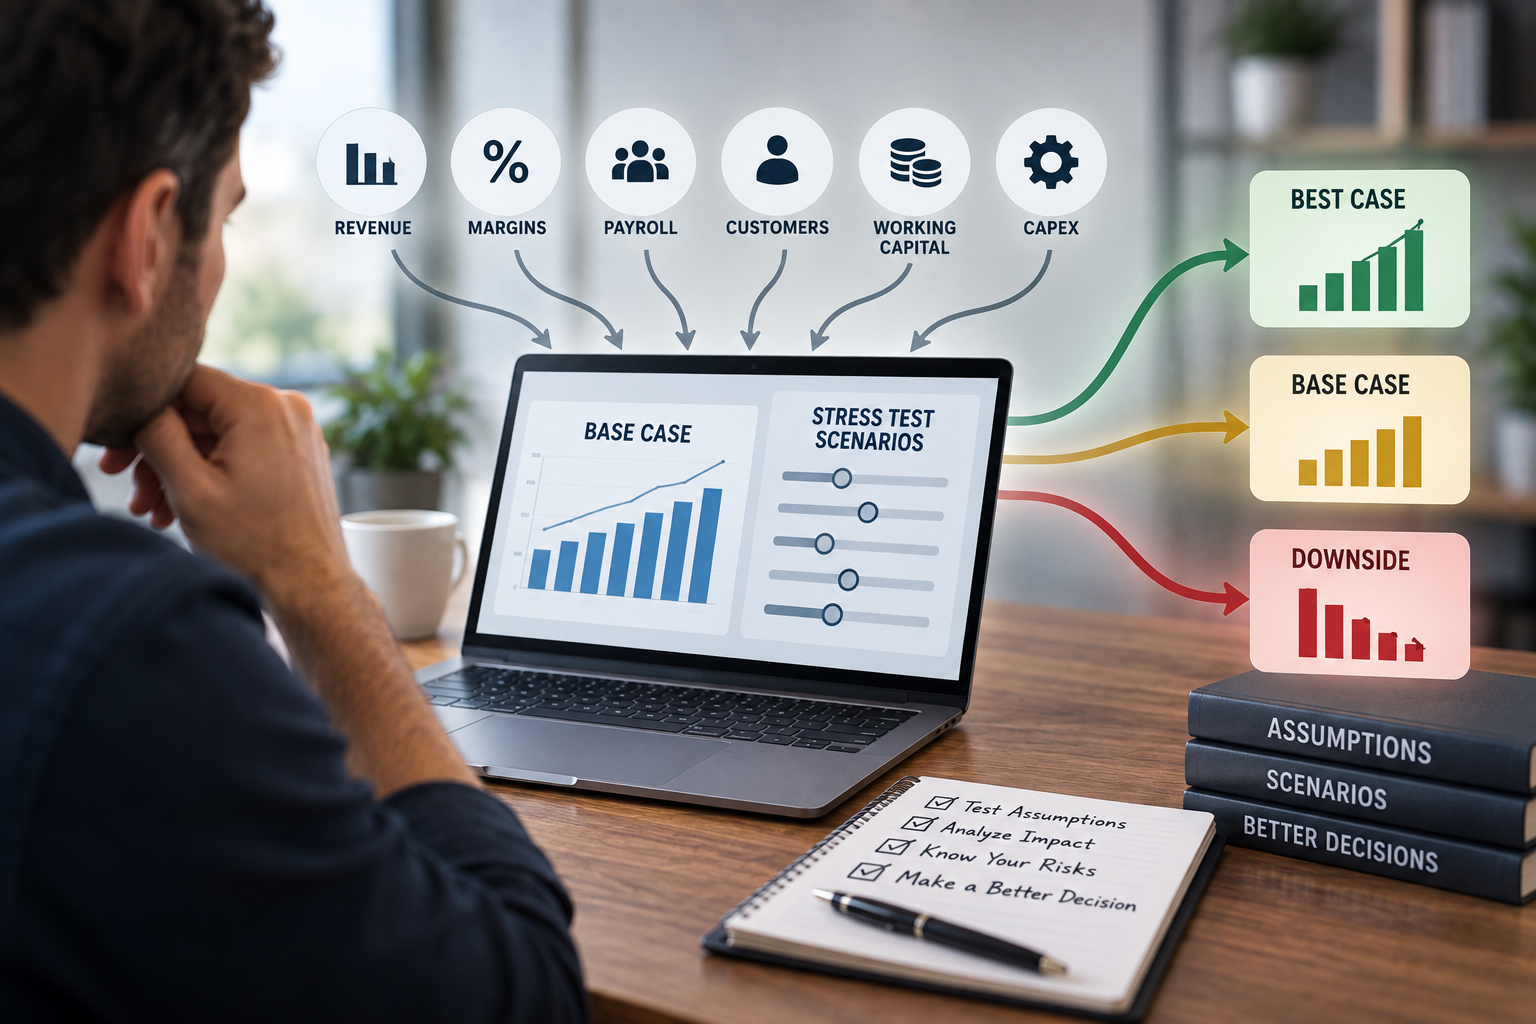
Creating financial projections can also help you test your assumptions before putting your money on the line. What happens if sales are lower than expected? How much working capital might you need? How many customers or sales will it take to cover your expenses?
If you don't know how to build financial projections yourself, StartSmart can automatically turn your business assumptions into a complete financial plan, projections, and supporting documentation without spreadsheets, formulas, or financial modeling experience. You can use StartSmart to plan one business completely free.
2. Not Understanding Your Target Customer
Trying to sell to everyone usually makes it harder to market effectively to anyone.
Before investing heavily in marketing, take the time to understand who is most likely to buy your product or service and why.
Consider questions such as:
- Who has the problem your product or service solves?
- How are they solving that problem today?
- What matters most when they choose a solution?
- How much are they willing to pay?
- Where do they look for information and recommendations?
- What would make them choose you instead of an alternative?
You don't need perfect answers before launching. In fact, conversations with prospective customers, early sales, and feedback may change some of your assumptions.
The important thing is to continue learning about your customers rather than building your business around assumptions that haven't been tested.
3. Not Using the Right Tools and Systems
Small business owners have access to technology that can automate or simplify work that once required significant time, specialized expertise, or additional employees.
That doesn't mean you need to adopt every new app or piece of technology.
Too many tools can create unnecessary costs and complexity of their own.
Instead, look for technology that solves a specific business problem. Accounting software can help organize your finances. Customer relationship management software can help manage prospects and customers. Project management tools can keep work organized. Automation can reduce repetitive administrative tasks.
The goal isn't to use more technology. It's to use the right technology where it can save time, reduce errors, provide better information, or help your business operate more efficiently.
4. Failing to Establish Clear Processes and Responsibilities
Even very small businesses benefit from clearly defined responsibilities and repeatable processes.
When nobody knows who owns a task, when something needs to happen, or how work should be completed, important responsibilities can easily fall through the cracks.
Document the processes your business depends on and establish clear ownership for recurring activities such as invoicing, customer follow-up, purchasing, payroll, marketing, and financial review.
As you hire employees or work with contractors, these processes become even more important.
You don't need layers of bureaucracy. You simply need enough structure so everyone understands what needs to happen, who is responsible for it, and when it needs to be completed.
5. Ignoring Intellectual Property and Legal Basics
Intellectual property may not be the first thing you think about when launching a business, but your company name, logo, website content, product designs, software, written materials, and other assets can become valuable parts of your business.
Depending on what you're creating, different protections may apply, including trademarks, copyrights, patents, contracts, and confidentiality agreements.
It's also important to make sure you're not unintentionally using intellectual property that belongs to someone else.
The protections your business needs will depend on what you sell and how you operate. When intellectual property is an important part of your business, getting appropriate legal guidance early can help prevent much more expensive problems later.
6. Spending Too Much, Too Soon
It's easy to spend money when you're excited about launching a business.
A larger office, another employee, expensive software, new equipment, additional inventory, or a bigger marketing budget may all seem like investments in growth.
But every commitment increases the amount of revenue your business needs to generate and can reduce the cash available when something unexpected happens.
Before taking on a major expense, understand how it will affect your cash flow and whether the business can realistically support it.
Accurate bookkeeping helps you understand where your money has already gone. Financial planning and forecasting help you think about where your money is going next.
Maintaining adequate cash reserves can also give your business more flexibility when sales are slower than expected or unexpected expenses arise.
7. Setting Prices Too Low
New business owners sometimes assume that charging less than competitors is the easiest way to attract customers.
But a lower price isn't necessarily a competitive advantage.
Your prices need to account for the direct cost of delivering your product or service as well as overhead, labor, taxes, payment processing, marketing, and the profit needed to sustain and grow the business.
Pricing too low can leave you with plenty of customers but little or no profit.
Instead of asking only, "What are my competitors charging?" consider what customers are willing to pay, what differentiates your offering, what it costs you to deliver, and what margins your business needs to be sustainable.
You can always test and adjust pricing as you learn more about your market.
8. Trying to Do Everything Yourself
When you're starting a business, doing things yourself can help keep costs down. But eventually, trying to handle every responsibility can become a constraint on the business.
Your time is limited.
Every hour spent on administrative work, bookkeeping, website maintenance, or another task outside your strengths is an hour you can't spend on customers, strategy, product development, sales, or other areas where you may create more value.
That doesn't mean you need to immediately hire a large team.
Contractors, freelancers, software, automation, professional advisors, and part-time employees can all help fill gaps as the business grows.
The key is recognizing which activities genuinely require your attention and which can eventually be delegated, outsourced, or automated.
Start Your Business With a Stronger Financial Plan
You won't eliminate every mistake when starting a business, and you don't need to have every answer before you launch.
But understanding your customers, managing your spending, setting sustainable prices, establishing good processes, and thinking carefully about your financial future can help you make better-informed decisions as your business gets off the ground.
A strong financial plan can be particularly valuable because many early business decisions are connected. Pricing affects revenue. Hiring affects expenses and cash flow. Financing creates repayment obligations. Sales expectations affect how much working capital you may need.
StartSmart helps you bring those assumptions together by automatically turning answers about your business into a complete financial plan, projections, and supporting documentation.
You can use StartSmart to plan one business completely free, without spreadsheets, formulas, or financial modeling experience.
Start building your financial plan with StartSmart for free today.