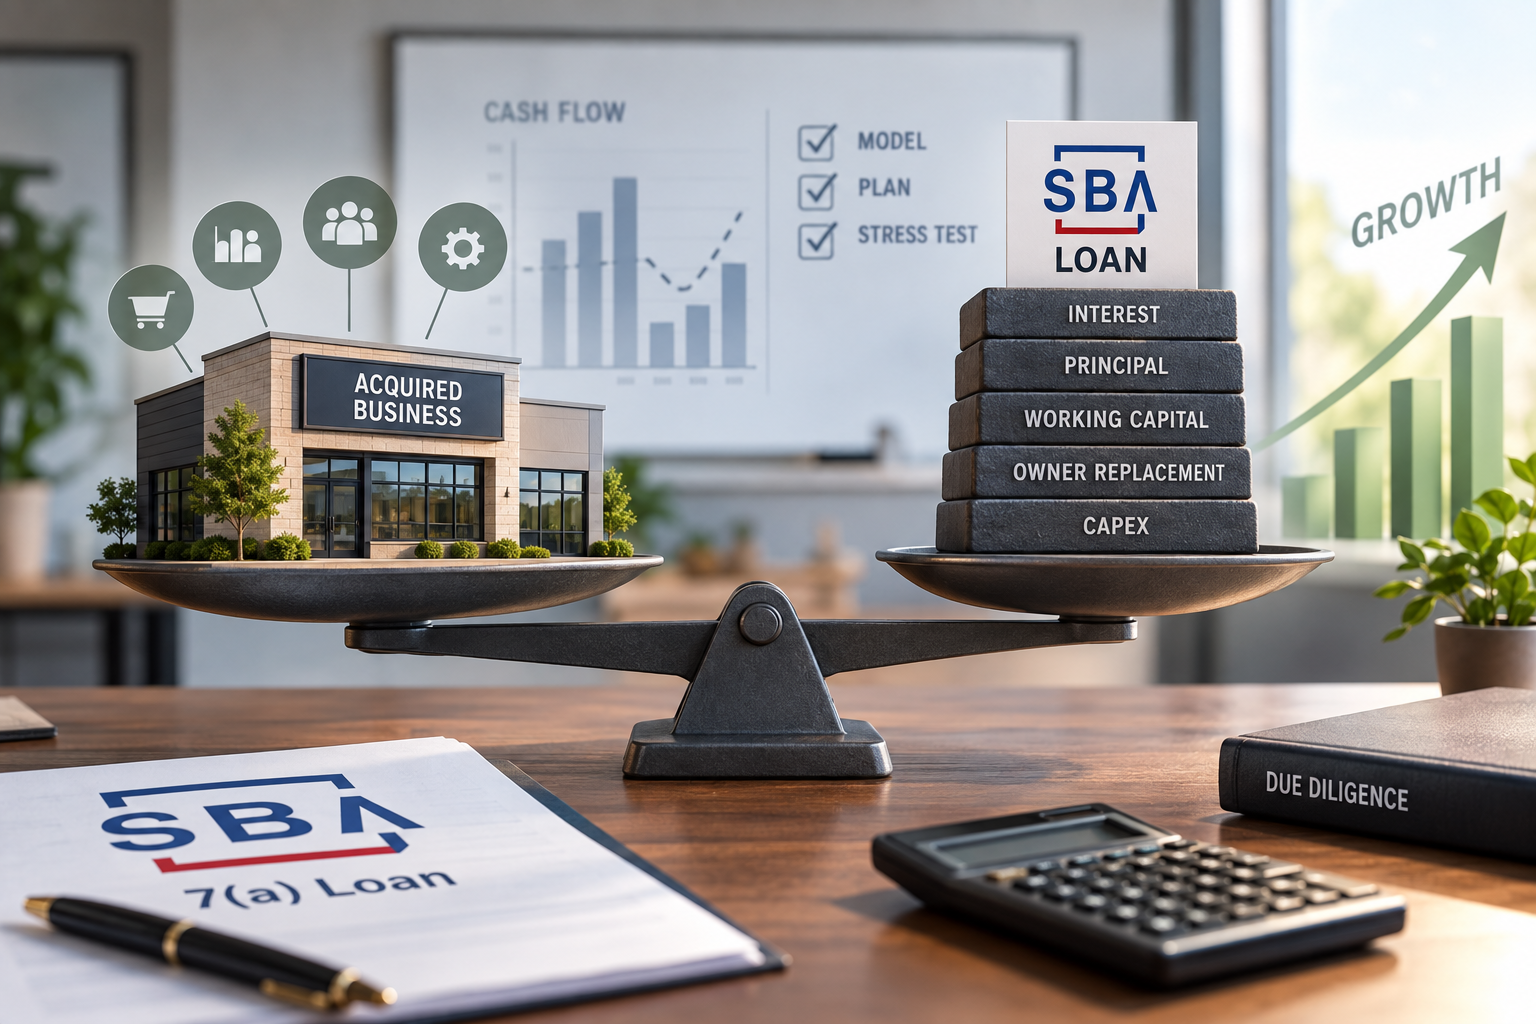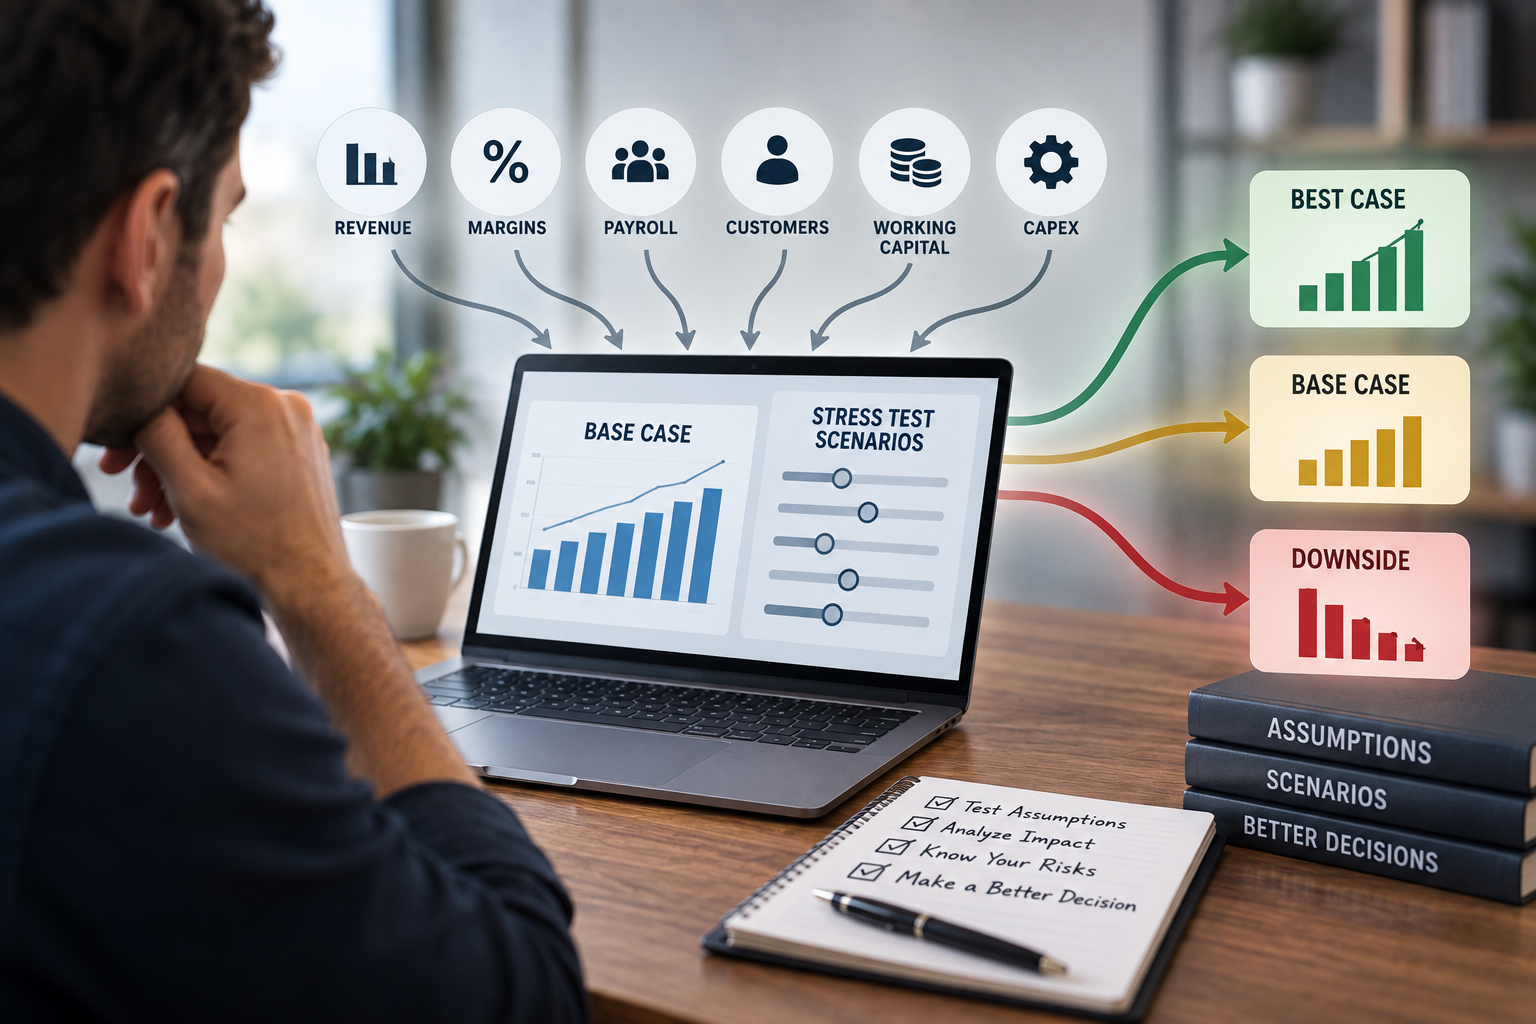
Stress testing a business acquisition means modeling how the company could perform if important financial assumptions turn out worse than expected, such as lower revenue, declining margins, customer losses, higher payroll, slower collections, or greater financing costs.
Most acquisition financial models answer a version of this question:
What happens if things go according to plan?
That's important.
But before buying a business, you should also ask:
What happens if they don't?
Perhaps revenue declines after the seller leaves.
A major customer could be lost.
Employees may require higher compensation.
Margins might tighten.
Customers could begin paying more slowly.
Equipment may need to be replaced sooner than expected.
Or acquisition debt could put more pressure on cash flow than anticipated.
None of these outcomes is guaranteed to happen.
That's exactly the point.
A stress test isn't a prediction of what will go wrong. It's a way to understand how financially sensitive the acquisition is when assumptions change.
Key Takeaways
- Stress testing evaluates how an acquisition could perform when important assumptions are worse than expected.
- Start with a reasonable financial forecast before creating downside scenarios.
- Test variables that materially affect the economics of the specific business rather than changing every assumption arbitrarily.
- Important stress tests can include revenue declines, margin compression, customer loss, payroll increases, owner replacement costs, slower collections, capital expenditures, and financing pressure.
- Test assumptions individually first so you can understand which variables have the greatest financial impact.
- Then combine plausible downside assumptions to understand how multiple pressures could affect the business simultaneously.
- Evaluate the effects on cash flow and liquidity, not only accounting profit.
- Stress testing isn't intended to determine whether you should buy a business. It helps you understand where the acquisition may be financially vulnerable before you commit.
What Is a Business Acquisition Stress Test?
A business acquisition stress test is a financial analysis that changes important assumptions in an acquisition forecast to evaluate how those changes could affect future performance.
Suppose your expected forecast assumes:
- Revenue grows 5%
- Gross margin remains stable
- Payroll increases 4%
- Existing customers remain
- Accounts receivable collections remain consistent
- No unexpected capital expenditures occur
Those assumptions may be reasonable.
But they're still assumptions.
A stress test asks what happens when one or more of them change.
For example:
What if revenue falls 10% instead of growing 5%?
What if gross margin declines three percentage points?
What if payroll increases 8%?
What if the largest customer leaves?
What if customers take an additional 20 days to pay?
What if the company needs $150,000 of unexpected equipment?
The purpose is to understand the financial consequences before those situations become real.
Why Should You Stress Test a Business Before Buying It?
When you buy a business, you're purchasing an operating company under uncertain future conditions.
Historical financial statements can show how the business performed under the seller.
Financial projections can estimate how it might perform under your ownership.
Stress testing goes one step further.
It asks:
How dependent is this acquisition on my assumptions being correct?
Consider two businesses with similar expected returns.
The first remains profitable and maintains adequate cash even if revenue falls 10%.
The second experiences severe cash pressure after only a 5% revenue decline.
Their expected forecasts may look similar.
Their financial resilience does not.
Understanding that difference can help you identify risks that aren't obvious from the Base forecast alone.
Start With a Reasonable Base Forecast
Before stress testing, establish a financial baseline.
Your Base forecast should represent a reasonable view of how you expect the business to perform based on:
- Historical financial performance
- Revenue trends
- Margins
- Payroll
- Operating expenses
- Working-capital behavior
- Capital expenditures
- Acquisition financing
- Your post-acquisition plans
The Base forecast shouldn't be deliberately optimistic or pessimistic.
It gives you a reference point.
You can then change individual assumptions and measure what happens relative to that baseline.
Without a baseline, stress testing becomes a collection of disconnected hypothetical numbers.
What Should You Stress Test When Buying a Business?
The most useful stress tests depend on the economics of the business you're evaluating.
A professional services firm may be highly sensitive to payroll and employee utilization.
A distributor may be more sensitive to inventory and supplier costs.
A company with significant customer concentration may be particularly vulnerable to losing one major account.
A highly leveraged acquisition may be sensitive to relatively small changes in cash flow.
Common variables to consider include:
- Revenue
- Gross margin
- Customer retention
- Payroll
- Owner replacement costs
- Operating expenses
- Accounts receivable
- Inventory
- Capital expenditures
- Acquisition financing
- Growth assumptions
- Multiple pressures occurring simultaneously
1. What Happens if Revenue Declines After the Acquisition?
Revenue is one of the most obvious variables to stress test.
Suppose a business generated $4 million in revenue last year and your Base forecast assumes approximately the same level of sales or modest growth.
Test alternatives such as:
- Revenue declines 5%
- Revenue declines 10%
- Revenue declines 20%
Then examine what happens to:
- Gross profit
- Operating profit
- Cash flow
- Working capital
- Debt coverage
- Cash balances
The important question isn't simply how much revenue disappears.
It's how the rest of the company's financial structure responds.
Many operating expenses don't decline automatically when revenue falls.
Rent remains due.
Salaried employees still need to be paid.
Insurance continues.
Software subscriptions remain.
Debt payments continue.
That means a 10% revenue decline can produce a much larger percentage decline in profit.
2. What Happens if Gross Margins Decline?
A business doesn't need to lose revenue to experience financial pressure.
It can sell the same amount and make less money from each sale.
Margin pressure can result from:
- Supplier price increases
- Wage increases
- Discounting
- Competitive pricing
- Product mix changes
- Customer mix changes
- Freight costs
- Material costs
- Operational inefficiency
Suppose a company generates $5 million in revenue at a 40% gross margin.
That produces:
$2 million of gross profit.
If gross margin falls to 35% while revenue remains unchanged, gross profit becomes:
$1.75 million.
That's a $250,000 reduction in gross profit without losing a dollar of revenue.
For a highly leveraged acquisition, that difference could materially affect cash flow.
3. What Happens if a Major Customer Leaves?
Customer concentration deserves its own stress test.
Suppose the company's largest customer represents 15% of annual revenue.
Instead of simply noting that concentration as a risk, model it.
Ask:
What happens financially if that customer disappears?
The answer isn't necessarily as simple as reducing revenue by 15%.
Some costs associated with serving the customer may also disappear.
Others won't.
You may also need to consider:
- Gross margin associated with that customer
- Dedicated employees
- Inventory
- Receivables
- Supplier commitments
- Replacement sales efforts
The objective is to translate an abstract concentration risk into a financial outcome you can evaluate.
4. What Happens if Payroll Costs Increase?
Payroll is often one of the largest expenses for a small business.
Stress-test assumptions around:
- Salary increases
- Hourly wage increases
- Benefits
- Bonuses
- Payroll taxes
- Additional hiring
- Employee turnover
- Recruiting costs
Suppose your Base forecast assumes payroll increases 3%.
What happens at 6%?
What happens at 10%?
If relatively small compensation changes eliminate most of the company's expected cash flow, that's useful information to know before buying it.
5. What Happens if You Need to Replace the Seller?
One of the most important acquisition stress tests may have nothing to do with economic conditions.
It may be the seller.
In many small businesses, the owner performs several jobs.
They may manage:
- Sales
- Operations
- Key customers
- Employees
- Vendors
- Finance
- Administration
If you aren't going to perform those responsibilities yourself, someone else will need to.
Suppose replacing the seller requires:
- $150,000 general manager
- $90,000 salesperson
- $30,000 additional administrative support
That's $270,000 of annual compensation before considering payroll taxes or benefits.
Those costs can materially change the economics of the acquisition.
Don't assume the seller's compensation represents the true cost of replacing the seller's work.
6. What Happens if Operating Expenses Are Higher Than Expected?
Acquisition forecasts often assume that many operating expenses remain relatively stable.
Stress-test that assumption.
Potential increases might include:
- Insurance
- Rent
- Utilities
- Marketing
- Software
- Professional services
- Repairs
- Travel
- Administrative costs
You don't necessarily need to increase every expense by an arbitrary percentage.
Focus on categories where uncertainty is meaningful.
If the seller has maintained unusually low spending in an area where you expect investment will be necessary, incorporate that into the analysis.
7. What Happens if Customers Pay More Slowly?
Profit doesn't necessarily equal cash.
Suppose customers historically pay invoices in approximately 35 days.
What happens if that increases to 50 or 60 days?
Revenue might remain unchanged.
Profit might remain unchanged.
But cash could become tied up in Accounts Receivable.
That matters because employees, suppliers, lenders, and other obligations still need to be paid.
Slower collections can therefore create liquidity pressure even when the Profit and Loss Statement looks healthy.
For an acquisition with significant debt payments, that pressure may be particularly important.
8. What Happens if the Business Needs More Inventory?
Businesses carrying inventory can experience a similar problem.
Suppose growth requires the company to purchase additional inventory months before receiving cash from customers.
Or perhaps supplier minimums increase.
Maybe inventory turns slow.
The company can be profitable while increasingly tying up cash on the Balance Sheet.
Stress testing inventory assumptions can help identify how much additional working capital the business might require.
9. What Happens if the Business Needs an Unexpected Capital Expenditure?
A business may have historically generated strong cash flow partly because it postponed investment.
After the acquisition, you might discover that the company needs:
- New vehicles
- Machinery
- Computers
- Manufacturing equipment
- Building improvements
- Technology infrastructure
Suppose $200,000 of equipment needs to be replaced during your first year.
How does that affect available cash?
Can the business finance it?
Does additional financing create more fixed obligations?
Could the business absorb the expenditure while continuing to meet acquisition debt payments?
Capital expenditure stress tests can be particularly important for asset-intensive businesses.
10. How Should You Stress Test Acquisition Debt?
Acquisition financing can amplify the consequences of weaker operating performance.
A business without significant debt may have flexibility when earnings decline.
A leveraged acquisition still has required debt obligations.
Stress-test whether the company can support its financing when operating performance is weaker than expected.
Ask:
What happens if revenue declines while debt payments remain unchanged?
What happens if margins fall?
What happens if working-capital requirements increase?
How much cash remains after required financing obligations?
How much financial cushion exists?
The objective isn't simply to determine whether the business can support debt under the Base forecast.
It's to understand what happens when the Base forecast doesn't occur.
Test One Assumption at a Time First
When beginning a stress test, change one major variable at a time.
For example:
Base: Revenue = $4 million
Stress Test A: Revenue −5%
Stress Test B: Revenue −10%
Stress Test C: Revenue −20%
Keep other assumptions unchanged initially.
This helps you understand the sensitivity of the business specifically to revenue.
Then repeat the exercise for margins, payroll, collections, or other important variables.
If you change everything simultaneously from the beginning, it becomes harder to understand what's driving the result.
Then Test Multiple Downside Assumptions Together
Real-world problems don't always happen one at a time.
A revenue decline may coincide with margin pressure.
A major customer loss may create excess staffing.
Slower collections may occur at the same time the company needs equipment.
After testing individual variables, create combined downside scenarios.
For example:
Moderate Downside
- Revenue −5%
- Gross margin −1 percentage point
- Payroll +5%
More Severe Downside
- Revenue −10%
- Gross margin −3 percentage points
- Payroll +8%
- Customer collections slow by 15 days
- $100,000 unexpected capital expenditure
The exact assumptions should reflect the business you're evaluating rather than generic percentages.
The purpose is to understand how several plausible pressures interact.
What Should You Measure in a Stress Test?
Don't evaluate only net income.
A useful stress test should examine how changing assumptions affect areas such as:
- Revenue
- Gross profit
- Operating profit
- Cash flow
- Cash balances
- Working capital
- Liquidity
- Debt coverage
- Assets
- Liabilities
- Overall financial health
Cash is particularly important.
A scenario may still show accounting profit while producing significant cash pressure because of debt payments, receivables, inventory, or capital expenditures.
What's the Difference Between a Forecast Model and a Scenario?
It can be useful to separate the underlying financial outlook from specific decisions or events you're testing.
A forecast model represents an overall outlook for the business.
For example:
- Bear
- Base
- Bull
- Custom
A scenario represents a set of changes or decisions evaluated within that forecast model.
Suppose your Base model represents the expected financial trajectory of the business.
You might create scenarios such as:
Base + Hire General Manager
Base + Increase Marketing
Base + Customer Loss
You could then evaluate similar decisions under a Bear model.
For example:
Bear + Hire General Manager
That can answer a more useful question than simply:
Can I afford to hire the manager?
Instead, you can ask:
Can I afford to hire the manager if the business performs worse than expected?
How Can RunSmart Help Stress Test a Business Acquisition?
Manually building stress tests in spreadsheets can require duplicating financial models, changing assumptions, maintaining formulas, and ensuring changes flow correctly through projected financial statements.
RunSmart by Projection Genie allows acquisition entrepreneurs to model different financial outlooks and scenarios using historical QuickBooks Online data as the foundation.
RunSmart automatically generates financial forecasts and supports Bull, Base, Bear, and Custom forecast models.
Within those models, users can create scenarios to evaluate how changes to the business may affect future financial performance.
For example, a prospective buyer could evaluate:
- Lower revenue
- Different expense assumptions
- New employees
- Compensation changes
- Additional spending
- Growth investments
RunSmart then reflects those assumptions through forward-looking financial projections, helping the buyer evaluate their potential effects on profitability, cash flow, and the company's financial position.
The goal isn't to tell the buyer whether to complete the acquisition.
It's to make the financial consequences of different assumptions easier to understand before committing to them.
How Can Historical QuickBooks Data Improve a Stress Test?
A stress test is more useful when it begins with an informed baseline.
If the seller provides appropriate QuickBooks Online access, historical accounting data can help establish patterns around:
- Revenue
- Expenses
- Margins
- Payroll
- Receivables
- Payables
- Assets
- Liabilities
- Cash flow
RunSmart uses historical QuickBooks data to automatically generate forward-looking forecasts.
The acquisition entrepreneur can then model changes relative to that baseline instead of beginning with an entirely blank financial model.
This creates a progression:
Historical financial data → Forecast model → Scenario → Financial impact
The historical information doesn't predict the future.
It gives the buyer a data-driven starting point for asking better questions about it.
What Is the Acquisition's Financial Breaking Point?
One particularly useful way to think about stress testing is to ask:
How much can change before this acquisition becomes financially uncomfortable?
For example:
How far can revenue fall before cash becomes constrained?
How much can margins decline before debt coverage becomes problematic?
How much additional payroll can the business support?
How much working capital can become tied up before liquidity becomes tight?
How large an unexpected expenditure can the company absorb?
This isn't necessarily one precise mathematical threshold.
The goal is to understand the financial cushion built into the acquisition.
An acquisition that works under several different conditions has a different risk profile from one that requires nearly every assumption to go according to plan.
Stress Testing Should Lead to Better Due-Diligence Questions
Stress testing can also improve your due-diligence process.
Suppose your analysis shows that a 10% revenue decline creates significant cash pressure.
That may lead you to investigate:
- Customer concentration
- Customer retention
- Contracts
- Seller relationships
- Competitive threats
- Historical revenue volatility
If the model is highly sensitive to gross margin, investigate:
- Supplier contracts
- Pricing
- Labor costs
- Product mix
- Historical margin volatility
If slower collections create problems, examine:
- Receivable aging
- Customer payment history
- Credit policies
- Bad debt
The financial model identifies what matters.
Due diligence helps determine how likely those risks may be.
Don't Use Stress Testing to Manufacture a Worst-Case Scenario
It's possible to make almost any business look terrible by stacking enough extreme assumptions together.
That's not particularly useful.
A stress test should help you understand plausible financial pressure, not create an apocalyptic scenario for its own sake.
The assumptions should be connected to the actual business.
A 30% revenue decline may be worth testing if the company has historically experienced significant volatility.
It may be less informative for a company with long-term contracts and highly predictable recurring revenue.
Similarly, customer-loss scenarios are particularly relevant when revenue is concentrated.
Inventory stress tests matter more for businesses carrying substantial inventory.
The best stress tests reflect how the specific business could realistically experience financial pressure.
Stress Test the Business You'll Own, Not the Business the Seller Owned
This distinction is critical.
You're not stress testing the seller's historical company.
You're stress testing the company after:
- Ownership changes
- Acquisition financing is introduced
- Seller responsibilities are replaced
- Your compensation is included
- Your hiring plans begin
- Your investment decisions occur
The seller may have operated the company successfully for 20 years with little debt.
That doesn't tell you how the business will behave with a large acquisition loan and a new management structure.
Build the stress test around the economics you're actually acquiring.
A Good Acquisition Model Should Survive More Than One Future
No forecast can tell you exactly what will happen after buying a business.
That's not what financial modeling is for.
A useful acquisition model helps you understand a range of possible outcomes.
What happens if the company performs approximately as expected?
What happens if it performs better?
What happens if it performs worse?
What happens if a particular risk occurs?
And what happens when multiple pressures appear at once?
Those questions give you a much more complete understanding of an acquisition than simply extending last year's financial statements into the future.
If you're evaluating a business that uses QuickBooks Online, RunSmart by Projection Genie can automatically analyze its historical financial data, generate forward-looking forecasts, and help you model Bull, Base, Bear, and Custom financial outlooks and different scenarios before you complete the acquisition.
Learn more about how RunSmart can help you model and stress test a business before you buy it.
Frequently Asked Questions About Stress Testing a Business Acquisition
What does it mean to stress test a business acquisition?
Stress testing a business acquisition means changing important financial assumptions to evaluate how weaker-than-expected conditions could affect the company after you buy it.
Examples include lower revenue, declining margins, higher payroll, customer losses, slower collections, unexpected capital expenditures, or increased financial pressure.
What should you stress test before buying a business?
The appropriate stress tests depend on the business, but buyers may evaluate changes to revenue, gross margin, customer retention, payroll, operating expenses, receivables, inventory, capital expenditures, working capital, and acquisition financing.
Focus on variables that could materially affect the economics of the specific company.
How much should you reduce revenue in a stress test?
There isn't one percentage that's appropriate for every business.
A buyer might evaluate several revenue declines, such as 5%, 10%, or 20%, but the assumptions should reflect the company's historical volatility, customer concentration, contracts, industry, and other relevant factors.
The purpose is to understand sensitivity rather than predict a specific decline.
Should you stress test one assumption at a time?
Testing one variable at a time can help identify which assumptions have the greatest financial impact.
After understanding individual sensitivities, buyers can also create combined scenarios in which multiple plausible pressures occur simultaneously.
Both approaches provide useful information.
Why is cash flow important when stress testing an acquisition?
A business may remain profitable while experiencing cash pressure.
Debt principal payments, receivables, inventory, working capital, and capital expenditures can consume cash without appearing as ordinary expenses on the Profit and Loss Statement.
That's why acquisition stress tests should generally evaluate cash flow and liquidity alongside profitability.
How do you stress test customer concentration?
If one customer represents a significant portion of revenue, a buyer can model what happens if that customer reduces spending or leaves.
The analysis should consider not only lost revenue but also the gross margin associated with the customer and any costs that would or wouldn't disappear with that revenue.
How do you stress test acquisition debt?
Buyers can model how the company performs under weaker operating conditions while required debt obligations remain.
For example, they can evaluate how lower revenue, declining margins, increased expenses, or greater working-capital needs affect cash available to support financing obligations.
What's the difference between a downside forecast and a scenario?
A downside forecast represents a broader weaker financial outlook for the business.
A scenario can represent a particular event, decision, or set of assumptions evaluated within an outlook.
For example, a Bear forecast model might represent weaker overall business performance, while a scenario could evaluate hiring a general manager within that Bear model.
What software can help stress test a business acquisition?
RunSmart by Projection Genie connects to QuickBooks Online, automatically generates financial forecasts, and allows acquisition entrepreneurs to evaluate different financial outlooks and scenarios.
Buyers can use Bull, Base, Bear, and Custom forecast models and model changes to revenue, expenses, staffing, compensation, and other assumptions to understand their potential effects on future financial performance.
Can stress testing tell you whether you should buy a business?
Stress testing doesn't determine whether you should complete an acquisition.
It helps you understand how the company's financial performance could change under different assumptions and where the acquisition may be particularly sensitive.
That information can be considered alongside valuation, financing, due diligence, operations, customers, employees, legal matters, taxes, and other factors involved in the acquisition decision.