From Searcher to CEO: Building Your First Financial Plan After Acquiring a Business
After acquiring a business, your first financial plan should turn the assumptions used to evaluate the acquisition into a working budget and forecast that tracks revenue, expenses, cash flow, debt, hiring, financial health, and actual performance under your ownership.
Before closing, financial analysis is largely about deciding whether an acquisition makes sense.
You analyze historical performance.
You evaluate financial health.
You build forecasts.
You model acquisition financing.
You stress-test assumptions.
Then the transaction closes.
At that point, the question changes.
You're no longer asking:
"What might happen if I buy this business?"
You're asking:
"What's actually happening now that I own it?"
The acquisition model that helped you evaluate the company can now become the foundation of your financial operating plan.
That means establishing a budget, tracking actual performance against your expectations, monitoring cash flow and financial health, updating forecasts as new information becomes available, and understanding where the business is deviating from the assumptions you made before closing.
The transition from searcher to CEO is also a transition from modeling possibilities to managing actual results.
Key Takeaways
- Don't abandon your acquisition model after closing. Convert its assumptions into an operating financial plan.
- Establish a budget based on the financial scenario you actually expect to execute.
- Separate the seller's historical performance from performance under your ownership.
- Monitor revenue, margins, expenses, payroll, cash flow, debt, and financial health rather than relying only on the bank balance.
- Compare actual results with your budget regularly to identify meaningful variances.
- Determine why a variance occurred before deciding how to respond to it.
- Update forward-looking forecasts as actual financial results provide new information.
- Monitor the assumptions that were most important to your acquisition thesis, such as customer retention, margins, owner replacement costs, hiring, or growth.
- Your first-year financial plan should evolve as you learn how the company actually operates under your ownership.
What Changes Financially After You Buy a Business?
The business may have existed for decades.
But from your perspective, closing creates a new financial starting point.
The company may now have:
- New ownership
- New acquisition debt
- Different management
- Different owner compensation
- New employees
- New strategic priorities
- New spending
- New growth plans
- Different cash requirements
Some things may remain almost exactly as they were under the seller.
Others may change quickly.
That's why you shouldn't assume the company's historical financial patterns will continue unchanged after closing.
The first year gives you an opportunity to compare what you expected before the acquisition with what actually happens afterward.
Start With the Acquisition Forecast You Already Built
If you created a detailed acquisition forecast before closing, don't start over.
Use it.
That model already contains assumptions about:
- Revenue
- Gross margin
- Payroll
- Operating expenses
- Management costs
- Hiring
- Financing
- Working capital
- Capital expenditures
- Growth
Those assumptions helped you decide whether the acquisition made financial sense.
Now they can become measurable expectations.
Suppose your acquisition model assumed:
- $4 million annual revenue
- 42% gross margin
- $900,000 payroll
- $300,000 annual debt service
- $150,000 of new marketing spending
- $250,000 ending cash
After closing, those numbers are no longer hypothetical assumptions used only to evaluate a transaction.
They can become benchmarks against which actual performance is measured.
Step 1: Convert Your Acquisition Scenario Into a Budget
A forecast and a budget serve related but different purposes.
A forecast estimates what could happen financially.
A budget establishes the financial plan you intend to operate against.
After the acquisition closes, identify the financial scenario that most closely represents your actual operating plan.
Then convert those assumptions into a budget.
Your budget may include monthly expectations for:
- Revenue
- Cost of goods sold
- Payroll
- Marketing
- Rent
- Insurance
- Software
- Professional services
- Other operating expenses
- Capital expenditures
- Debt-related cash requirements
- Cash balances
Monthly planning is especially useful because annual totals can hide problems.
A company could finish near its annual revenue target while experiencing substantial shortfalls during individual months.
Those timing differences can matter when payroll and debt payments are due throughout the year.
Step 2: Establish Your Financial Baseline at Closing
You need to know where you're starting.
Document the company's financial position around the acquisition date.
Depending on the transaction, important information may include:
- Cash
- Accounts Receivable
- Inventory
- Accounts Payable
- Existing debt
- New acquisition debt
- Fixed assets
- Other assets and liabilities
- Working capital
This helps create a clean distinction between:
The business you purchased
and
The business operating under your ownership.
That distinction becomes increasingly valuable as you begin evaluating your own results.
Step 3: Identify the Assumptions That Matter Most
Not every line in your financial model deserves equal attention.
Identify the assumptions that had the greatest influence on your decision to buy the company.
These might include:
- Customer retention
- Revenue growth
- Gross margin
- Seller transition
- Management replacement
- Employee retention
- Payroll
- Marketing performance
- Working capital
- Capital expenditures
- Debt service
Suppose your acquisition works financially only if the company maintains at least a 38% gross margin.
That margin deserves close attention.
If the acquisition depends heavily on retaining three large customers, monitor those relationships.
If your forecast assumes the seller can be replaced by one general manager, pay attention to whether that assumption proves correct.
Your financial plan should focus attention on the assumptions that could materially affect the acquisition.
Step 4: Track Revenue Against Your Plan
Revenue will naturally receive significant attention after closing.
But don't simply ask whether sales are up or down.
Compare actual revenue with:
- Budget
- Prior periods
- Historical seasonality
- Your current forecast
Suppose your budget called for $350,000 of monthly revenue but actual revenue is $315,000.
That's a $35,000 shortfall.
The next question is:
Why?
Potential explanations could include:
- Customer loss
- Seasonal timing
- Lower sales volume
- Pricing changes
- Delayed contracts
- Seller transition
- Sales staffing
- Market conditions
The variance identifies the difference.
Understanding the business explains it.
Step 5: Monitor Gross Margin, Not Just Revenue
A new owner can become overly focused on growing sales.
But revenue growth doesn't necessarily produce better financial performance.
Suppose revenue exceeds your budget by 10%.
That sounds positive.
But if gross margin falls from an expected 40% to 32%, the company may generate less gross profit than planned despite the additional sales.
Monitor:
- Revenue
- Cost of Goods Sold
- Gross Profit
- Gross Margin
together.
This can help you determine whether growth is actually contributing to the financial results you expected.
Step 6: Track Payroll and Workforce Changes
Payroll is often one of the largest costs in a small business.
It's also one of the areas most likely to change after an acquisition.
You may:
- Replace the seller
- Add managers
- Give raises
- Replace departing employees
- Add salespeople
- Hire for growth
- Change benefits
Compare actual payroll with what you assumed before the acquisition.
If payroll is higher than expected, determine why.
Perhaps compensation needed to increase to retain key employees.
Maybe replacing the seller required more people than expected.
Or perhaps you're hiring ahead of growth.
The important question isn't simply:
"Are we over budget?"
It's:
"Why are we over budget, and does the reason change our expectations for the business?"
Step 7: Monitor Operating Expenses
Review significant operating expenses against your plan.
Potential categories include:
- Marketing
- Insurance
- Rent
- Utilities
- Software
- Professional services
- Repairs
- Travel
- Office expenses
- Other overhead
Not every budget variance requires action.
Suppose legal expenses exceed budget because of one-time post-acquisition work.
That has a different implication from software expenses running 30% above budget every month.
Separate:
Timing differences
from
One-time variances
from
Structural changes.
That distinction helps you determine whether the forecast itself needs to change.
Step 8: Pay Close Attention to Cash Flow
Profitability doesn't eliminate the need to monitor cash.
After an acquisition, cash may be affected by:
- Debt principal payments
- Interest
- Accounts Receivable
- Inventory
- Accounts Payable
- Taxes
- Capital expenditures
- Hiring
- Growth investments
A company can perform close to its Profit and Loss budget while cash falls below expectations.
Suppose revenue and profit are approximately on plan.
But customers are paying 15 days slower than expected.
Accounts Receivable increases.
Cash becomes tied up.
At the same time, acquisition debt payments continue.
This is why your post-acquisition financial plan should include both profitability and cash-flow monitoring.
Step 9: Monitor the Company's Financial Health
Individual financial statements tell only part of the story.
You should also monitor whether the company's broader financial health is improving or deteriorating.
Areas to evaluate include:
Profitability
Is the business producing adequate earnings from its operations and resources?
Liquidity
Does it have sufficient short-term financial resources to meet obligations?
Solvency
Can it support its longer-term financial obligations?
Efficiency
How effectively is it managing receivables, payables, inventory, and assets?
Capitalization
How dependent is the company on debt?
These areas can move in different directions.
The business might become more profitable while liquidity deteriorates.
Revenue may increase while customers take longer to pay.
Return on equity may improve while leverage increases.
Looking across multiple dimensions helps you understand what's happening beneath the headline numbers.
Step 10: Compare Budget vs. Actual Performance
One of the most useful post-acquisition financial disciplines is Budget vs. Actual analysis, often abbreviated BvA.
The concept is straightforward:
What did you expect to happen?
versus
What actually happened?
Suppose your monthly budget included:
- Revenue: $350,000
- Payroll: $90,000
- Marketing: $15,000
- Operating Income: $45,000
Actual results are:
- Revenue: $330,000
- Payroll: $98,000
- Marketing: $14,000
- Operating Income: $25,000
The important result isn't simply that operating income missed budget by $20,000.
You want to understand why.
Revenue was $20,000 below plan.
Payroll was $8,000 above plan.
Marketing was $1,000 below plan.
Other financial relationships may have contributed as well.
Budget vs. Actual analysis turns your pre-acquisition assumptions into measurable operating expectations.
What Should You Do When Actual Results Miss the Budget?
A variance isn't automatically a problem.
And beating the budget isn't automatically evidence that everything is going well.
Start by understanding the cause.
Suppose marketing spending exceeds budget by $20,000.
If that overspending produces profitable new revenue, you may view it differently from an unexpected recurring cost producing no apparent benefit.
Or suppose payroll is under budget because three critical positions remain unfilled.
The favorable expense variance may actually signal an operating problem.
This is why financial management requires context.
The numbers identify where actual performance differs from the plan.
You determine what those differences mean.
Step 11: Update Your Forecast
Your original acquisition forecast was created using the information available before closing.
After operating the business for several months, you know more.
Perhaps:
- Revenue is more seasonal than expected
- A customer left
- Margins are stronger
- Payroll is higher
- A planned hire isn't necessary
- Working-capital requirements are larger
- Marketing is producing better results
- Equipment needs replacement sooner
- Customers pay more slowly
Your forecast should evolve as you learn.
Suppose your original annual revenue forecast was $4 million.
After six months, actual results and updated expectations suggest $3.7 million is more realistic.
Continuing to compare everything against an outdated $4 million forecast doesn't make the original assumption more useful.
Update the forward-looking view.
The budget can remain the record of what you originally intended.
The forecast can reflect what you currently expect.
That distinction is powerful:
Budget = What we planned
Actual = What happened
Forecast = What we now expect
Step 12: Revisit Your Downside Scenarios
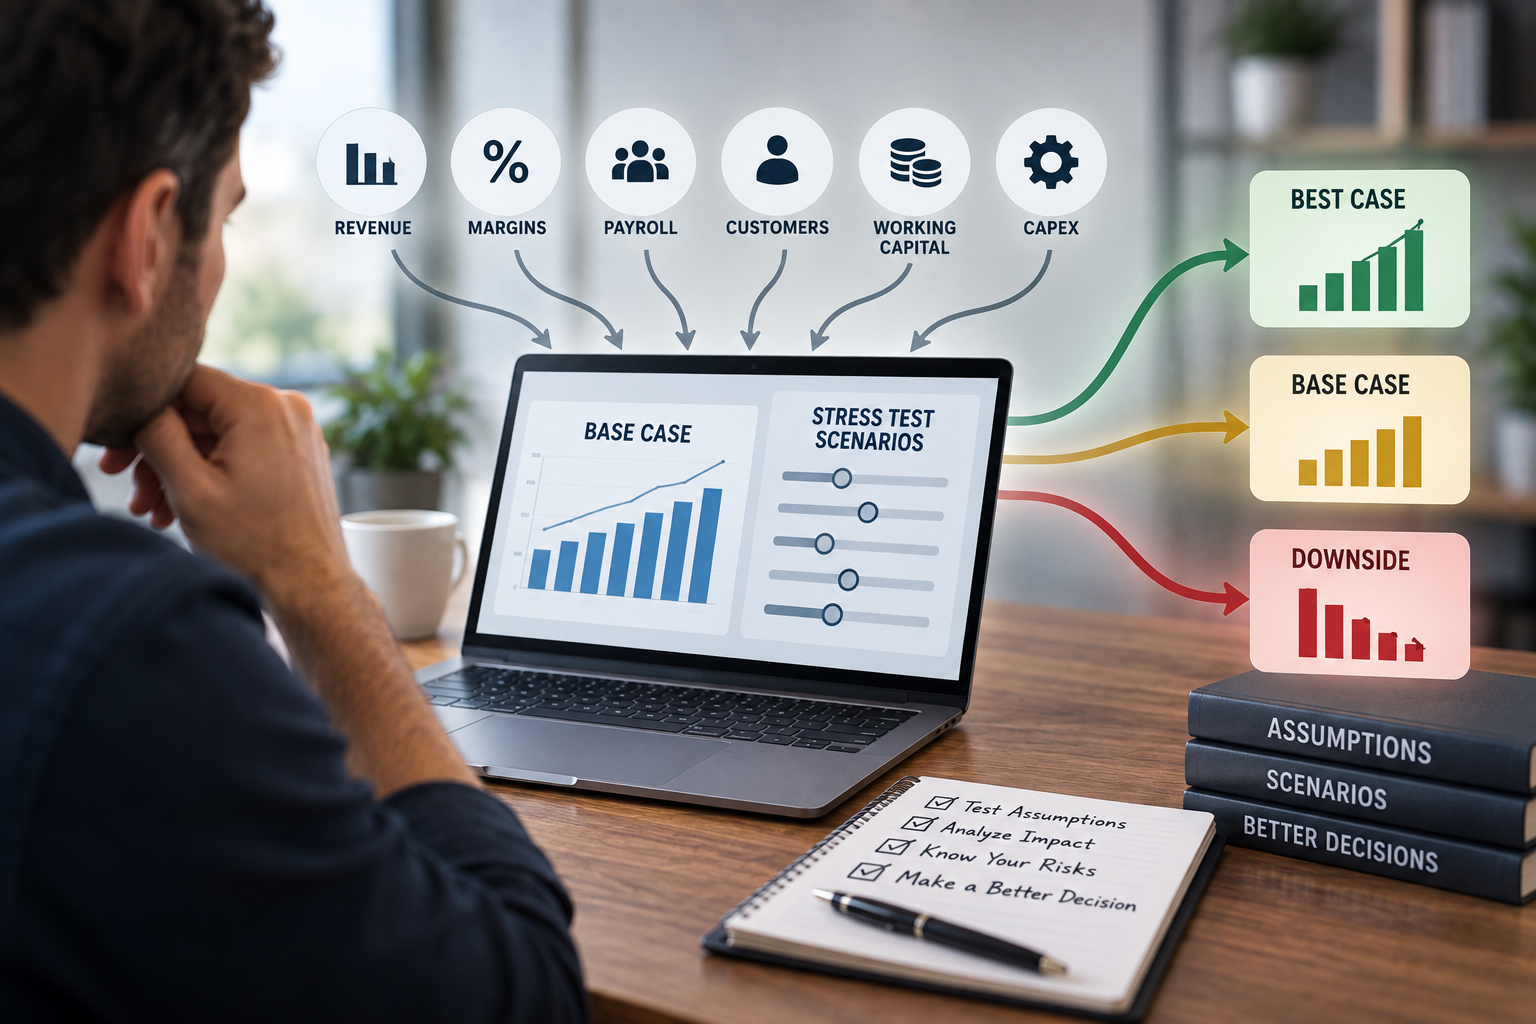
Before buying the business, you may have stress-tested scenarios such as:
- Revenue decline
- Customer loss
- Margin compression
- Payroll increases
- Slower collections
- Unexpected capital expenditures
After closing, revisit those scenarios using what you've learned.
Some risks may now appear less significant.
Others may be more important than you originally believed.
For example, perhaps customer concentration concerned you before closing, but retention remains strong.
Meanwhile, you discover the business requires much more working capital during its busy season than you expected.
Your risk analysis should evolve with your understanding of the company.
How Often Should You Review Financial Performance After an Acquisition?
For many businesses, a monthly financial review provides a useful operating rhythm because accounting periods can be closed and compared consistently.
Your monthly review might examine:
- Revenue
- Gross margin
- Major expenses
- Payroll
- Profitability
- Cash flow
- Cash balance
- Working capital
- Budget variances
- Financial health
- Forward forecast
- Major risks
Quarterly reviews can provide a broader perspective on trends and strategic decisions.
The appropriate cadence depends on the business.
A company experiencing significant cash pressure may require much more frequent cash monitoring than a financially stable business.
Build a Repeatable Financial Operating Rhythm
Financial planning becomes more useful when it becomes a process rather than an occasional project.
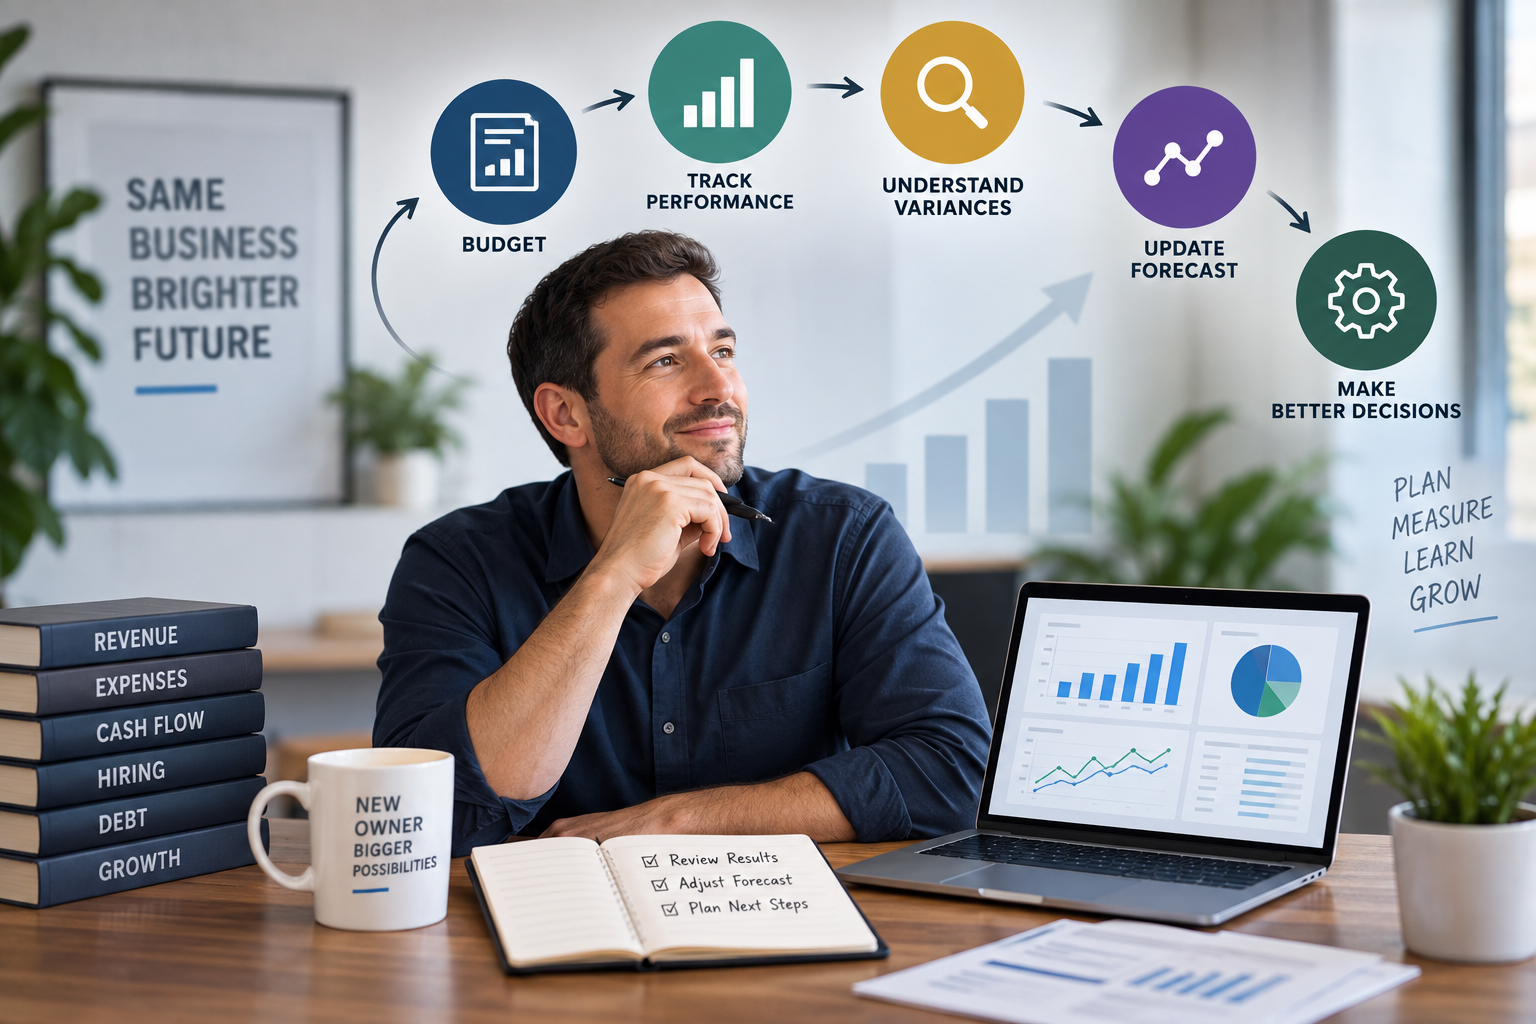
A simple cycle might be:
1. Close the month
Make sure the accounting records are complete.
2. Review actual performance
Understand what happened.
3. Compare results with budget
Identify material differences.
4. Review financial health
Look beyond profit to liquidity, solvency, efficiency, and capitalization.
5. Update the forecast
Incorporate what you've learned.
6. Evaluate upcoming decisions
Model hiring, spending, financing, or growth changes before committing.
7. Repeat
This turns financial planning into an ongoing management discipline.
How Can RunSmart Help After You Buy the Business?
Before the acquisition, RunSmart by Projection Genie can help analyze historical QuickBooks Online data, generate forward-looking forecasts, evaluate financial health, and model different scenarios.
After the acquisition, the same financial intelligence can support a different purpose:
Operating the company.
RunSmart connects to QuickBooks Online and analyzes completed accounting periods to provide an updated view of the company's financial performance.
You can use RunSmart to:
- Analyze historical and current financial performance
- Generate forward-looking financial forecasts
- Monitor financial health
- Track key financial metrics
- Model hiring, spending, and other business scenarios
- Convert a scenario into a budget
- Compare budget with actual performance
- Review projected Profit and Loss, Cash Flow, and Balance Sheet statements
- Identify emerging financial risks
This creates continuity between acquisition analysis and post-acquisition management.
Turn Your Acquisition Scenario Into a RunSmart Budget
Suppose you modeled the acquisition using a scenario that included:
- Your expected revenue
- New management costs
- Planned hiring
- Marketing investment
- Other post-acquisition expenses
Once that scenario represents the plan you intend to execute, RunSmart allows you to convert it into a budget.
Actual QuickBooks results can then be compared with that budget as new completed months become available.
Instead of rebuilding your acquisition assumptions in a separate spreadsheet, your planning process can move from:
Forecast → Scenario → Budget → Actual Results
That makes it easier to see where the business is behaving differently from what you expected before closing.
Use Budget vs. Actual Analysis Across the Financial Statements
Budgeting shouldn't necessarily stop at the Profit and Loss Statement.
RunSmart supports Budget vs. Actual analysis across:
- Profit and Loss
- Cash Flow
- Balance Sheet
That broader view can be particularly useful after an acquisition.
For example, revenue and operating expenses might be close to budget while Accounts Receivable is significantly higher than expected.
The Profit and Loss Statement may therefore appear relatively healthy while cash is weaker than planned.
Looking across the financial statements helps identify those relationships.
Monitor Business Health as the Acquisition Evolves
RunSmart's Business Health Scorecard evaluates 13 financial metrics across five dimensions:
Profitability
- Operating Margin
- Return on Assets
- Return on Equity
Liquidity
- Working Capital
- Quick Ratio
Solvency
- Interest Coverage
- Debt to Assets
- Fixed-Charge Coverage Ratio
Efficiency
- Days Sales Outstanding
- Days Payable Outstanding
- Days Sales of Inventory
- Asset Turnover
Capitalization
- Debt to Capitalization
These measures can help you monitor whether the financial characteristics of the company are changing under your ownership.
For example:
Is liquidity deteriorating?
Is debt becoming more significant relative to assets?
Are customers paying more slowly?
Are margins improving?
Is asset efficiency changing?
The objective isn't to manage the business according to a single score.
It's to make important financial changes easier to identify and investigate.
Model Decisions Before You Make Them
Your financial planning needs don't end once you've completed the acquisition.
You'll eventually face decisions such as:
Should I hire another salesperson?
Can I afford a general manager?
What happens if I increase marketing?
How could a major expense affect cash flow?
What if revenue grows faster than expected?
What happens if sales decline?
Instead of making those decisions based entirely on intuition, you can model their potential financial effects before committing.
This is where post-acquisition forecasting becomes particularly valuable.
You're no longer modeling whether to buy the company.
You're modeling how to run it.
Don't Let the Bank Balance Become Your Financial Dashboard
It's tempting for a new owner to manage primarily by looking at the company's bank account.
Cash matters enormously.
But a bank balance doesn't tell you:
- Whether margins are deteriorating
- Whether receivables are increasing
- Whether profitability is declining
- Whether debt is becoming harder to support
- Whether expenses are exceeding plan
- Whether future cash flow is projected to weaken
- Whether the business is becoming more or less financially healthy
The bank account tells you how much cash exists today.
Financial planning helps you understand why it's there and what may happen next.
Your First 100 Days Should Include Financial Learning
The first months after acquiring a company are an opportunity to test what you believed during due diligence against what you observe as the owner.
Pay attention to questions such as:
Which assumptions were accurate?
Which costs did I underestimate?
Which revenue drivers are stronger than expected?
Which customers matter most?
How predictable is cash flow?
What causes margins to change?
How much working capital does the company really need?
Which expenses are truly fixed?
What financial information do I need to make decisions faster?
You don't need to change everything immediately.
You need to understand the company you're now responsible for operating.
The First Year Is About Replacing Assumptions With Evidence
Before the acquisition, you had models.
After the acquisition, you begin accumulating evidence.
Every completed month gives you more information about how the business performs under your ownership.
Over time:
Assumptions become actual results.
Expected margins become observed margins.
Projected payroll becomes actual payroll.
Estimated working-capital needs become real cash requirements.
Customer-retention assumptions become actual customer behavior.
That's why post-acquisition financial planning shouldn't be static.
Your understanding of the company should become more precise as you operate it.
From Searcher to CEO
During the search process, financial analysis helps you decide which businesses deserve further investigation.
During due diligence, it helps you understand the company's financial condition.
During financing, it helps you evaluate the acquisition structure.
During stress testing, it helps you understand what happens when assumptions change.
After closing, those same disciplines become part of running the company.
The objective changes from evaluating an opportunity to managing an operating business.
But the underlying questions remain connected:
Where have we been?
Where are we now?
Where might we be heading?
What happens if we make this decision?
If your acquired business uses QuickBooks Online, RunSmart by Projection Genie can help you automatically transform accounting data into financial health insights, forward-looking forecasts, budgets, Budget vs. Actual analysis, and scenarios so you can understand how the business is performing and model important decisions before committing to them.
The acquisition may be complete.
The financial planning has just begun.
Learn more about using RunSmart to manage and plan the business after your acquisition.
Frequently Asked Questions About Financial Planning After Buying a Business
What should you do financially after buying a business?
After closing, establish the company's starting financial position, convert your acquisition assumptions into an operating budget, monitor actual financial performance, track cash flow and financial health, compare results with your plan, and update forecasts as new information becomes available.
The objective is to move from acquisition analysis to ongoing financial management.
Should you keep using your acquisition financial model after closing?
Yes, if the model reflects the assumptions underlying your acquisition.
Those assumptions can become benchmarks for actual performance.
As you gain operating experience, the original model can also help you identify where the business is performing differently from what you expected.
What's the difference between a budget and a forecast after an acquisition?
A budget generally represents the financial plan you intend to operate against.
A forecast represents your current expectation of what may happen.
After several months of actual results, the forecast may change while the original budget remains useful as a comparison against the initial plan.
What should you monitor during the first year after buying a business?
Important areas can include revenue, gross margin, payroll, operating expenses, profitability, cash flow, working capital, debt obligations, customer collections, capital expenditures, financial health, and performance against budget.
The most important metrics depend on the economics and risks of the specific business.
How often should you review financial performance after an acquisition?
Monthly financial reviews can provide a useful recurring operating rhythm for many businesses because completed accounting periods can be compared consistently.
Cash may need to be monitored more frequently, particularly when liquidity is tight or the business has significant financial obligations.
What is Budget vs. Actual analysis?
Budget vs. Actual analysis compares planned financial performance with actual results.
It can help identify where revenue, expenses, cash flow, assets, liabilities, or other financial measures differ from expectations.
The next step is determining why the variance occurred and whether it changes the company's forward-looking expectations.
Should you update your forecast when actual results differ from your acquisition plan?
Yes. A forecast is most useful when it reflects the information currently available.
If actual performance reveals that revenue, expenses, margins, working capital, or other assumptions are materially different from what you expected before closing, updating the forecast can provide a more realistic forward-looking view.
What financial metrics should a new business owner monitor?
The appropriate metrics depend on the business.
Financial measures can include revenue, margins, profitability, cash flow, working capital, liquidity, debt coverage, receivables, payables, inventory, asset efficiency, and capitalization.
Operational or industry-specific KPIs may also be important.
Can QuickBooks be used for post-acquisition financial planning?
QuickBooks Online provides accounting data that can serve as the foundation for post-acquisition analysis.
Financial planning software can then use that historical and current accounting information to create forecasts, analyze trends, evaluate financial health, and compare actual performance with a budget.
How can RunSmart help after acquiring a business?
RunSmart by Projection Genie connects to QuickBooks Online and automatically analyzes financial data to provide forward-looking forecasts, financial health analysis, KPIs, scenarios, budgets, and Budget vs. Actual tracking.
An acquisition entrepreneur can use it before closing to analyze and model the business and after closing to monitor actual performance, update expectations, and model future business decisions.